Arizona loan guide • October 2026
Conventional Loans in Arizona: 3% Down and 2026 Conforming Limits
Conventional loans are mortgages that are not part of a government program such as FHA, VA or USDA. In Arizona they often start near three percent down through Fannie Mae HomeReady and Freddie Mac Home Possible, and they follow the 2026 FHFA conforming loan limits. This guide covers those limits, private mortgage insurance rules, HomeReady and Home Possible options, and when conventional beats FHA or VA for Arizona homes and condos. Every figure links to an official source.
Key facts for this loan type
- Conventional means the loan is not part of a specific government program such as FHA, VA or USDA (CFPB).
- 2026 conforming loan limit for a 1-unit home: $832,750 in most counties, including Arizona; high-cost ceiling $1,249,125 (FHFA).
- Fannie Mae HomeReady and Freddie Mac Home Possible allow as little as 3% down for buyers at or below 80% of area median income (Fannie Mae, Freddie Mac).
- With less than 20% down on a conventional loan, private mortgage insurance is typically required (CFPB).
- You can usually request PMI cancellation when the loan balance reaches 80% of the original value, and it generally ends automatically at 78% if you are current (CFPB).
- Conventional loans can finance a primary residence, and many lenders also offer conventional options for second homes or investment properties under separate rules.
Talk to a dedicated full-time local agent
What this loan type is
The CFPB conventional loans page explains that “conventional” simply means the loan is not part of a specific government program. Most conventional purchase loans that stay within the FHFA size caps are conforming loans backed to Fannie Mae or Freddie Mac standards.
Conventional financing can cost less than FHA for buyers with stronger credit, but it can also be harder to qualify for. Compare official Loan Estimates before you choose. The CFPB loan options guide is a clear place to start.
2026 conforming loan limits for conventional loans in Arizona
FHFA announced the 2026 conforming loan limit values on November 25, 2025. For a 1-unit home, the baseline limit is $832,750 and the high-cost ceiling is $1,249,125. Arizona counties use the baseline $832,750 limit.
| 2026 conventional limit (1-unit) | Amount |
|---|---|
| Baseline conforming limit (most U.S. counties, including Arizona) | $832,750 |
| High-cost ceiling | $1,249,125 |
Loans above the conforming limit are jumbo (non-conforming) and follow lender-specific rules, often with larger down payments and stricter credit standards. Most buyers in Mesa, Phoenix, Chandler, Gilbert, Tempe, Glendale, Peoria, Queen Creek and Tucson shop within the conforming cap.
Talk with a dedicated full-time local agent about pre-approval →
Conventional loans with 3% down: HomeReady and Home Possible
Fannie Mae HomeReady allows as little as 3% down when borrower income is at or below 80% of area median income. When every borrower is a first-time buyer, a homeownership education course is required. Freddie Mac Home Possible also allows 3% down with the same 80% income cap and an education requirement for first-time buyers.
On a $300,000 purchase price, three percent down is $9,000. That is less cash than FHA’s 3.5% down on the same price, but you will typically pay private mortgage insurance until you build enough equity. Ask your lender whether HomeReady, Home Possible or a standard conventional program fits your income and credit.
Conventional loans cost compared with FHA and VA
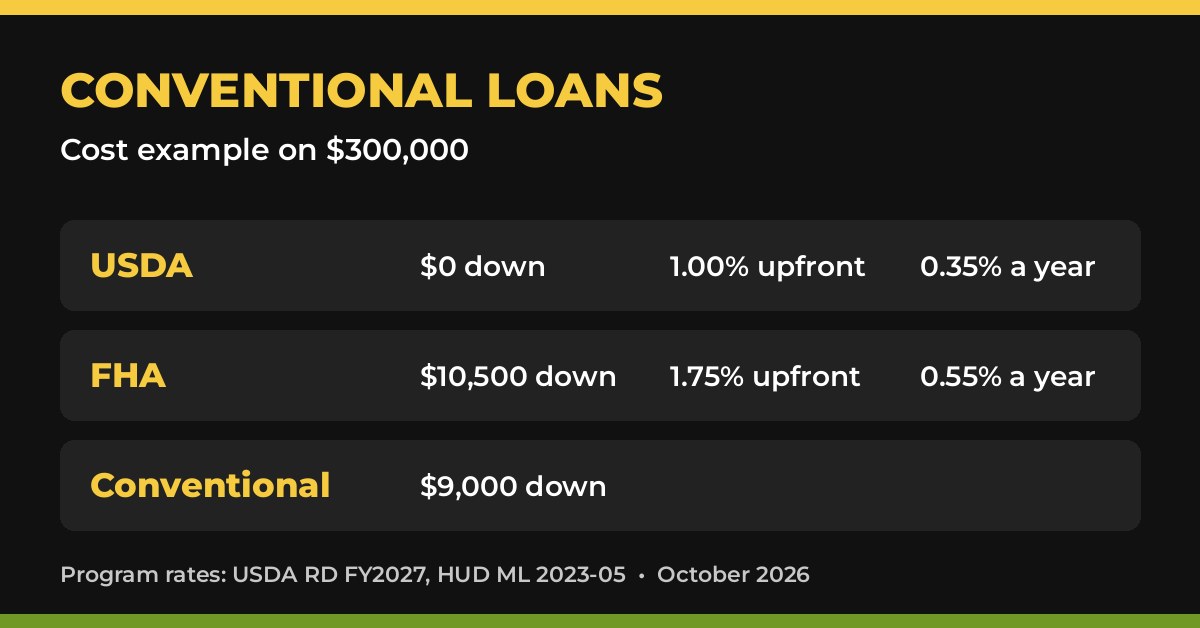
Here is simple math on a $300,000 example price. It is an illustration, not a loan quote, and it leaves out interest, taxes, insurance, PMI premium amounts and closing costs.
| Conventional loans example on $300,000 | Down payment | Upfront program fee | Mortgage insurance |
|---|---|---|---|
| Conventional (3% down) | $9,000 | None set by the program | PMI typical under 20% down |
| Conventional (20% down) | $60,000 | None set by the program | Usually none |
| FHA (3.5% down) | $10,500 | $5,066.25 (1.75% of $289,500) | 0.55% annual on many 30-year loans |
| VA (first use, $0 down) | $0 | $6,450 (2.15% funding fee) | None |
Sources: CFPB on PMI, HUD ML 2023-05, VA.gov funding fee. Compare Loan Estimates before you choose.
Private mortgage insurance rules
If you put down less than 20% on a conventional loan, you will typically need private mortgage insurance, or PMI, according to the CFPB PMI explainer. PMI protects the lender, not you, and is usually paid as a monthly premium added to your payment.
Under federal rules explained by the CFPB, you can usually request cancellation when the principal balance reaches 80% of the home’s original value, and the servicer must generally end PMI automatically at 78% if you are current on payments. That cancellation path is a common reason buyers choose conventional over FHA once their credit and down payment support it.
Talk with a dedicated full-time local agent about pre-approval →
Conventional loans compared with FHA, VA and USDA
Choose conventional when your credit and income support it and you want a path to cancel PMI. Choose FHA when you need more flexible credit rules and can accept mortgage insurance for the life of many loans. Choose VA when you are eligible for the VA guaranty and want $0 down with no monthly mortgage insurance. Choose USDA when the address is rural-eligible and household income fits the cap.
Read our FHA loans guide, VA loans guide, USDA loans guide and first-time home buyers guide for the full comparison.
Down payment help in Arizona
The Home Plus program offers up to 4% assistance for down payments and closing costs statewide, with a forgivable option after 5 years and an income limit of $155,386 as of April 6, 2026. Ask a participating lender whether Home Plus can pair with HomeReady, Home Possible or another conventional product.
First-time buyers in Maricopa and Pima counties can also ask about programs listed by the Arizona Department of Housing. Funding and rules change, so confirm availability before you write an offer.
Documents lenders ask for on conventional loans
Most conventional pre-approvals start with two years of tax returns or W-2s, 30 days of pay stubs, two months of bank and investment statements, a photo ID, and a full list of monthly debts. Self-employed borrowers usually need profit-and-loss statements and business bank records. Gift funds need a gift letter that meets Fannie Mae or Freddie Mac rules.
If you are using HomeReady or Home Possible, keep proof of income at or below 80 percent of area median income and your homebuyer education certificate when every borrower is a first-time buyer. The CFPB home buying guide walks through the paperwork timeline from pre-approval to closing. Bring the same packet when you compare Loan Estimates so each lender prices the same facts.
Arizona buyers often close in 21 to 45 days once the contract is signed. Your agent can schedule inspections early and keep appraisal repairs from slowing the loan. If your credit or debt ratios are tight, ask whether a slightly larger down payment or a co-borrower improves pricing before you shop homes.
Keep your rate lock calendar next to inspection and appraisal dates. If a repair request stretches the timeline, ask the lender whether the lock can be extended and what the fee is before you agree to a new close date. A dedicated full-time local agent coordinates those dates with the title company so conventional financing stays on track.
Conventional loans buyer checklist for Arizona
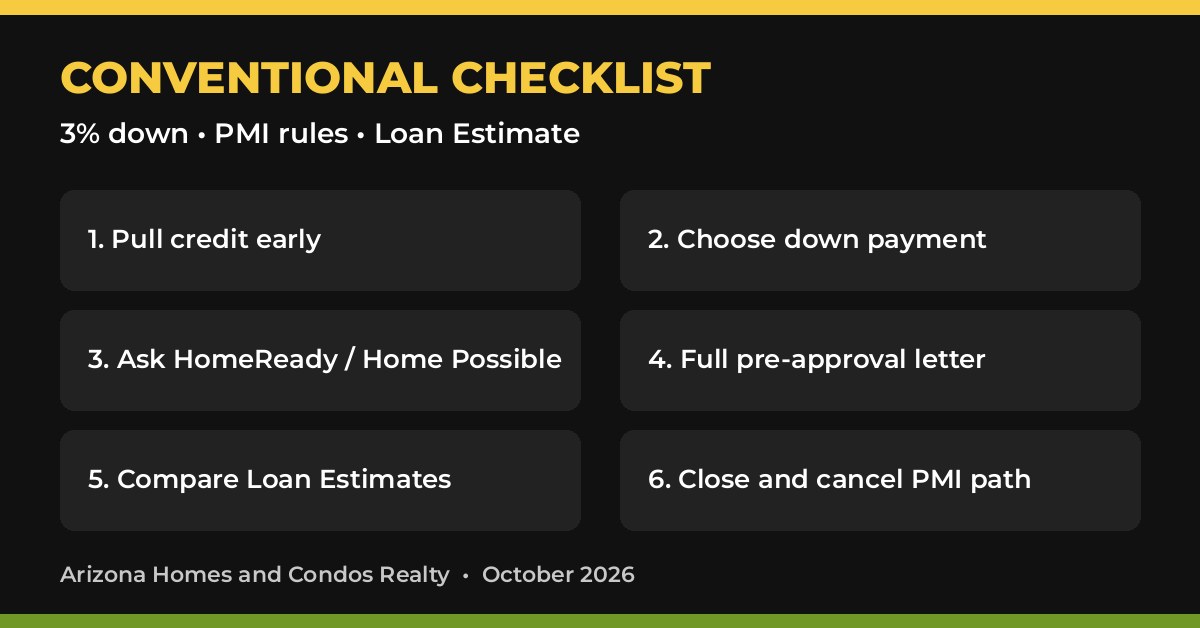
Pull credit early, choose a down-payment target, ask about HomeReady and Home Possible when income fits, and get a full pre-approval before weekend tours. Compare at least two Loan Estimates line by line, then plan the path to cancel PMI once you reach 80 percent equity based on the original value, as the CFPB explains.
5 tips for conventional loan pre-approval in Arizona
- Pull your credit early. Conventional pricing is sensitive to score and debt ratios.
- Decide on three, five, ten or twenty percent down. More down usually means less PMI and sometimes a better rate.
- Ask about HomeReady and Home Possible if your income is at or below 80% of area median income.
- Get a full pre-approval before you tour, so your agent can target the right price band.
- Compare Loan Estimates from more than one lender, as the CFPB recommends.
FAQ for Arizona buyers
What is a conventional loan?
A conventional loan is a mortgage that is not part of a government program such as FHA, VA or USDA. Most size-limited conventional loans are conforming loans that follow Fannie Mae or Freddie Mac rules.
What is the 2026 conventional loan limit in Arizona?
FHFA set the 2026 baseline conforming loan limit for a 1-unit home at $832,750. Arizona counties use that baseline. The national high-cost ceiling is $1,249,125.
Can I buy with a small down payment on a conventional loan?
Yes, if you qualify for programs such as Fannie Mae HomeReady or Freddie Mac Home Possible, which allow three percent down for buyers at or below 80% of area median income.
Do conventional loans require PMI?
Usually yes, when you put down less than 20%. PMI is typically monthly and can often be canceled once you reach 80% equity based on the original value, with automatic termination generally at 78% if you are current.
Is conventional better than FHA?
It depends. Conventional can be cheaper over time if you can cancel PMI and you qualify for a strong rate. FHA can be easier to qualify for with lower scores. Compare Loan Estimates for both.
How do I get conventional pre-approval in Arizona?
Share income, assets and debts with a lender and ask for a full pre-approval letter. Use the form on this page and a dedicated full-time local agent can help you connect with a lender and shop homes inside your approval.
Official sources
Last Updated: October 2026. Every figure on this page comes from the official source linked here; we checked each one on October 25, 2026.
- FHFA, 2026 conforming loan limits (announced Nov. 25, 2025)
- Fannie Mae, HomeReady mortgage
- Freddie Mac, Home Possible 3% down
- CFPB, Conventional loans
- CFPB, What is private mortgage insurance?
- CFPB, Understand the different kinds of loans
- CFPB, Buying a house
- Home Plus program, down payment assistance and income limit (updated April 6, 2026)
- Arizona Department of Housing, programs for homebuyers
- VA.gov, VA-backed Veterans home loans
- CFPB, FHA loans
Ready for conventional loan pre-approval?
Tell us where you want to live and the price band you have in mind. A dedicated full-time local agent will help you compare conventional, FHA and VA paths, line up pre-approval, and keep your Arizona closing on schedule. Start with the form below and we will follow up the same business day when we can.
Talk with a full-time agent about pre-approval
Tell us the city and the home type. A dedicated full-time local agent will reach out, and we can connect you with a lender for conventional pre-approval if you want one.
Do you know anyone looking to buy or sell real estate in Arizona? Share our website with them so they are fully informed.
Call Arizona Homes and Condos Realty at (480) 490-4865 or visit ArizonaHomesandCondos.com.