Arizona loan guide • October 2026
Manufactured Home Mortgage in Arizona: How to Get a 30 Year Mortgage
A manufactured home mortgage lets you buy a factory-built home and the land under it with a 30 year mortgage, the same long term used for site-built homes. This guide covers manufactured home loans from FHA, Fannie Mae and Freddie Mac, the 2026 Arizona loan limits, and seven steps to get approved. Every figure links to an official source.
Manufactured home mortgage key facts
- FHA allows a 30 year mortgage on a manufactured home and its site when the home is classified as real estate (HUD).
- FHA requires at least 400 square feet, a build date after June 15, 1976, the HUD certification label and a permanent foundation (HUD).
- 2026 FHA limit for a 1-unit home: $557,750 in Maricopa and Pinal counties, $609,500 in Coconino County and $541,287 in the rest of Arizona (HUD).
- Fannie Mae minimum down payment: 5% on a standard manufactured home and 3% on an MH Advantage home (Fannie Mae).
- Freddie Mac Home Possible allows 3% down and lists manufactured homes as eligible (Freddie Mac).
- 2026 conforming loan limit for a 1-unit home: $832,750 (FHFA).
Get help buying a manufactured home in Arizona
Tell us the city and the home type. A dedicated full-time local agent will reach out, and we can connect you with a loan officer if you want one.
What a manufactured home mortgage is
A manufactured home is built in a factory to the federal HUD code and then moved to a lot. A manufactured home mortgage is a real estate loan secured by both the home and the land, which is what makes a 30 year mortgage possible. When the home is not tied to land you own, the financing is usually a personal property loan, often called a chattel loan.
The difference matters. The CFPB report on manufactured housing finance found that chattel borrowers face higher denial rates and pay higher interest rates than borrowers with manufactured home loans titled as real property. If you plan to buy the land and set the home on a permanent foundation, you open the door to FHA, Fannie Mae and Freddie Mac programs.
In Arizona, manufactured homes are common on acreage lots and in smaller towns such as Chino Valley, Camp Verde, Florence and Wickenburg. Your agent can confirm whether a listed home is already titled as real property before you write an offer.
FHA manufactured home loans with a 30 year mortgage
FHA insures these loans under its standard Title II program. The HUD reference guide for manufactured homes lists these rules for a home and its site financed together:
- The home must have at least 400 square feet of floor area.
- It must have been built after June 15, 1976, and carry the HUD certification label.
- It must be classified as real estate.
- The mortgage covers the home and the site, with a term of no more than 30 years.
- The home must sit on a permanent foundation and keep its permanent chassis.
- The finished grade must be at or above the 100-year flood elevation.
FHA allows 3.5% down with a credit score of 580 or higher, and buyers with scores from 500 to 579 are limited to 90% loan-to-value, per HUD Mortgagee Letter 2026-11. Mortgage insurance applies to every FHA loan. Read our FHA loans guide for the full breakdown.
Manufactured home mortgage limits in Arizona for 2026
FHA sets a maximum loan amount by county. The figures below are the 2026 limits for a 1-unit home from the HUD loan limit lookup, effective for FHA case numbers assigned on or after January 1, 2026.
| Arizona county | 2026 FHA limit, 1-unit home |
|---|---|
| Maricopa | $557,750 |
| Pinal | $557,750 |
| Coconino | $609,500 |
| All other Arizona counties | $541,287 |
Conventional manufactured home loans follow the 2026 conforming loan limit of $832,750 for a 1-unit home, set by FHFA. Most manufactured homes in Arizona sell well below both limits, so the limit rarely decides the deal. Your down payment, credit and debt-to-income ratio usually do.
Conventional manufactured home loans from Fannie Mae and Freddie Mac
Fannie Mae manufactured home financing requires a minimum down payment of 5% on a standard manufactured home and 3% on an MH Advantage home, which is a newer home built with certain site-built style features. The home must be titled as real property.
Freddie Mac Home Possible offers 3% down for buyers with income at or below 80% of the area median, and Freddie Mac lists manufactured homes as eligible property types. Fannie Mae HomeReady has a similar income cap. Both offer 30-year terms, and both can be paired with Arizona down payment assistance where the loan program allows it.
7 steps to a manufactured home mortgage in Arizona
- Check your credit. Pull your free reports and fix errors before you apply.
- Get pre-approved. Ask a loan officer which programs they offer, since not every loan program covers factory-built homes.
- Pick the right home. Look for a build date after June 15, 1976, the HUD label and at least 400 square feet.
- Confirm the land and title. The home should be titled as real estate with the land, or the seller should be able to convert it before closing.
- Plan the foundation. FHA and conventional loans need a permanent foundation. Budget for an engineer’s certification if one is missing.
- Order the appraisal and inspection. Comparable manufactured home sales support the value.
- Lock your rate and close. Compare the rate, mortgage insurance and closing costs on each offer.
A dedicated full-time local agent keeps the title, foundation and appraisal steps moving at the same time so your closing date holds.
Manufactured home mortgage costs and down payment help
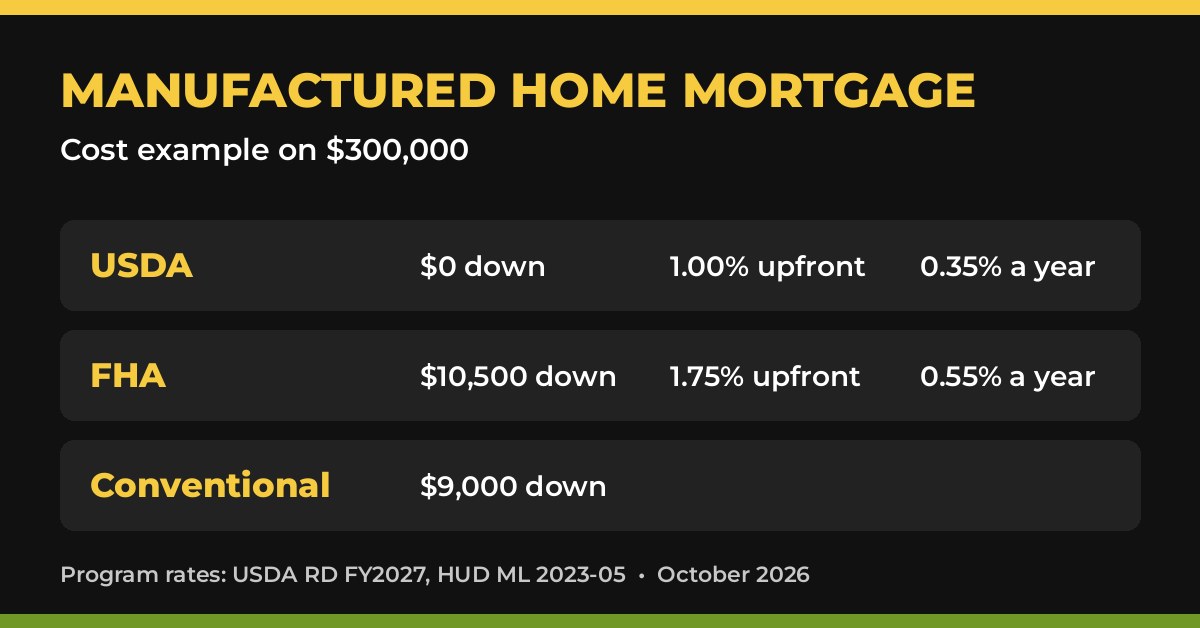
Here is simple math on a $300,000 example price, using the published program rates. It is an illustration, not a loan quote, and it leaves out interest, taxes, insurance and closing costs.
| Manufactured home mortgage example on $300,000 | Down payment | Upfront fee | Annual fee, first year |
|---|---|---|---|
| USDA guaranteed | No down payment | $3,000 (1.00%)* | $1,050 (0.35%) |
| FHA | $10,500 | $5,066.25 (1.75% of $289,500) | about $1,592 (0.55%) |
| Conventional (3% down) | $9,000 | None set by the program | Varies by loan program and credit |
From our experience
*The USDA upfront guarantee fee can be paid by the seller as a seller concession, so a USDA buyer can truly put 0% down out of pocket.
Earnest money can be as little as $250 when you write an offer asking the seller to agree to your USDA 100% financing terms. The amount is negotiable and set in your purchase contract.
Rates come from the USDA RD FY2027 fee notice and HUD Mortgagee Letter 2023-05. The FHA annual figure is an estimate on the starting balance. Ask your loan officer for a Loan Estimate, the standard three-page form the CFPB explains, to compare real offers line by line.
The Home Plus program offers up to 4% assistance for down payments and closing costs, available statewide. Its forgivable option is a deferred second mortgage forgiven after 5 years, and at least one borrower completes a homebuyer education course. The program lists an income limit of $155,386, updated April 6, 2026, and says Home Plus is available year-round and does not deplete its funding. Ask a participating loan officer whether Home Plus can be added to your manufactured home mortgage.
Land, title and foundation checks before you buy
Most problems with a manufactured home mortgage come from paperwork, not the house. Before you make an offer, ask the seller for the HUD certification label numbers, the data plate and proof of how the home is titled. If the home is still titled as personal property, ask your title company how it can be converted to real property in Arizona before closing, because your loan officer will want to see that record.
Next, look at the foundation. The HUD guide requires a permanent foundation built to the manufacturer’s instructions or an approved standard. Loan officers often ask for a licensed engineer’s letter. If the home sits in a flood zone, the finished grade must be at or above the 100-year flood elevation. Ask about wells, septic systems and road access too, since rural lots in places like Morristown and Dewey-Humboldt often have them.
Manufactured home mortgage options in rural Arizona
Many Arizona manufactured homes sit on acreage outside the metro areas. If the address is in an eligible rural area, a USDA guaranteed loan with 100% financing may be worth asking your loan officer about. Check the address on the official USDA eligibility map, then compare your household income with the USDA RD income limits: $129,250 for a household of 1 to 4 in Maricopa and Pinal counties and $122,800 in most other Arizona counties.
On October 16, 2026, the center points of Chino Valley, Dewey-Humboldt, Camp Verde, Florence, Coolidge, Eloy, Kearny, Safford and Holbrook fell outside the shaded ineligible areas. Your manufactured home mortgage still needs to meet the loan program’s property rules, so confirm both before you write an offer.
Which manufactured home loans fit your plan
Use this quick comparison to start the conversation with your loan officer. It reflects the program rules published by each official source as of October 2026.
| Program | Minimum down | Longest term | Who it suits |
|---|---|---|---|
| FHA | 3.5% (580+ score) | 30 years | Buyers with modest savings or lower scores |
| Fannie Mae standard MH | 5% | 30 years | Buyers with steady credit and some savings |
| Fannie Mae MH Advantage | 3% | 30 years | Buyers of newer homes with MH Advantage features |
| Freddie Mac Home Possible | 3% | 30 years | Buyers at or below 80% of area median income |
If the home sits in a rural area, a USDA guaranteed loan with 100% financing may also be worth asking about. See our USDA loans guide and the first-time home buyers guide.
Manufactured home mortgage FAQ
Can I get a 30 year mortgage on a manufactured home?
Yes. FHA allows a term of up to 30 years when the home and site are financed together as real estate, and Fannie Mae and Freddie Mac also offer 30 year terms on eligible manufactured homes.
How much do I need down for a manufactured home mortgage?
FHA requires 3.5% down with a credit score of 580 or higher. Fannie Mae requires 5% on a standard manufactured home and 3% on an MH Advantage home. Freddie Mac Home Possible allows 3% down.
What is the oldest manufactured home FHA will finance?
FHA requires the home to have been built after June 15, 1976, and to carry the HUD certification label.
Does the home need a permanent foundation?
Yes. FHA requires a permanent foundation and the home must be classified as real estate. Fannie Mae requires the home to be titled as real property.
What is the 2026 FHA loan limit in Maricopa County?
The 2026 FHA limit for a 1-unit home in Maricopa County is $557,750, the same as Pinal County, according to the HUD loan limit lookup.
Can I buy a manufactured home with no money down?
A USDA guaranteed loan offers 100% financing in eligible rural areas. Ask your loan officer whether the specific home and lot qualify, and check the address on the official USDA eligibility map.
Manufactured home mortgage official sources
Last Updated: October 2026. Every figure on this page comes from the official source linked here; we checked each one on October 16, 2026.
- HUD Single Family reference guide, manufactured homes (archived)
- HUD Mortgagee Letter 2025-23, FHA 2026 loan limits
- HUD FHA mortgage limits lookup, Arizona CY2026
- HUD Mortgagee Letter 2026-11 (Oct. 8, 2026), FHA credit score tiers
- FHFA, 2026 conforming loan limits (announced Nov. 25, 2025)
- Fannie Mae, manufactured home financing
- Freddie Mac, Home Possible 3% down
- CFPB, Manufactured Housing Finance report (May 27, 2021)
Ready to buy a manufactured home with a 30 year mortgage?
Tell us where you want to live. A dedicated full-time local agent will help you find a home that fits FHA or conventional rules and keep your closing on schedule.
Talk with a full-time agent about your manufactured home purchase
Tell us the city and the home type. A dedicated full-time local agent will reach out, and we can connect you with a loan officer if you want one.
Do you know anyone looking to buy or sell real estate in Arizona? Share our website with them so they are fully informed.
Call Arizona Homes and Condos Realty at (480) 490-4865 or visit ArizonaHomesandCondos.com.