Arizona loan guide • October 2026
FHA Loans in Arizona: 3.5% Down and 2026 Loan Limits
FHA loans let you buy a home with 3.5% down and flexible credit rules. This guide covers the 2026 FHA loan limits for every Arizona county, the credit score tiers, mortgage insurance costs and five tips to get approved. Every figure links to an official source.
FHA loans key facts
- FHA allows the minimum down payment with a credit score of 580 or higher; scores from 500 to 579 are limited to 90% loan-to-value (HUD).
- 2026 FHA limit for a 1-unit home: $557,750 in Maricopa and Pinal counties, $609,500 in Coconino County and $541,287 in all other Arizona counties (HUD).
- National 2026 FHA limits for a 1-unit home range from a floor of $541,287 to a ceiling of $1,249,125 (HUD).
- Upfront mortgage insurance premium: 1.75% of the base loan amount (HUD).
- Annual mortgage insurance on most 30-year loans with 3.5% down: 0.55% for the life of the loan (HUD).
- The FHA program is for a primary residence and requires mortgage insurance on every loan (CFPB).
Find a home that fits FHA financing
Tell us the city and the home type. A dedicated full-time local agent will reach out, and we can connect you with a loan officer if you want one.
What FHA loans are and how 3.5% down works
These are mortgages insured by the Federal Housing Administration, part of HUD. Approved loan officers originate the loan and FHA insures it, which allows smaller down payments and lower credit scores than many conventional programs. The CFPB guide to FHA loans notes that down payments can be as low as 3.5% and that loan limits vary by county.
The cost example below shows the down payment and FHA mortgage insurance on a sample price. Your loan officer will add closing costs and prepaid items to build your full cash-to-close number.
FHA loans credit score rules
HUD sets two credit tiers. Buyers with a minimum decision credit score of 580 or higher can get maximum financing, which is the lowest FHA down payment. Buyers with scores from 500 to 579 are limited to 90% loan-to-value, which means 10% down. These tiers are restated in HUD Mortgagee Letter 2026-11, issued October 8, 2026.
Individual loan programs can set stricter rules of their own, called overlays, so two loan officers may give you different answers. If one says no, ask another. Paying down card balances and fixing report errors before you apply are the fastest ways to raise a score.
FHA loan limits in Arizona for 2026
FHA loan limits cap how much FHA will insure in each county. These are the 2026 limits for a 1-unit home from the HUD FHA loan limit lookup, set under HUD Mortgagee Letter 2025-23 for case numbers assigned on or after January 1, 2026.
| Arizona county | 2026 FHA limit, 1-unit home |
|---|---|
| Maricopa | $557,750 |
| Pinal | $557,750 |
| Coconino | $609,500 |
| All other Arizona counties | $541,287 |
The national floor for a 1-unit home is $541,287 and the high-cost ceiling is $1,249,125. In Maricopa and Pinal counties, the 2026 limit for a 2-unit property is $714,000. Use the HUD lookup for 3-unit and 4-unit limits.
Most Arizona FHA buyers in Mesa, Phoenix, Glendale, Surprise, Buckeye and Casa Grande shop well within these FHA loan limits. In Flagstaff, the higher Coconino County limit applies.
FHA loans mortgage insurance costs
Every FHA loan carries mortgage insurance. Under HUD Mortgagee Letter 2023-05, the upfront premium is 1.75% of the base loan amount. The annual premium depends on the loan size, term and loan-to-value. For a 30-year loan of $726,200 or less with less than 5% down, the annual premium is 0.55% and lasts for the life of the loan. With 10% or more down, it is 0.50% and ends after 11 years.
Many buyers refinance into a conventional loan later to drop the annual premium once they build equity. Compare the total monthly cost of FHA against a conventional 3% down program before you choose.
FHA loans cost compared with USDA and conventional
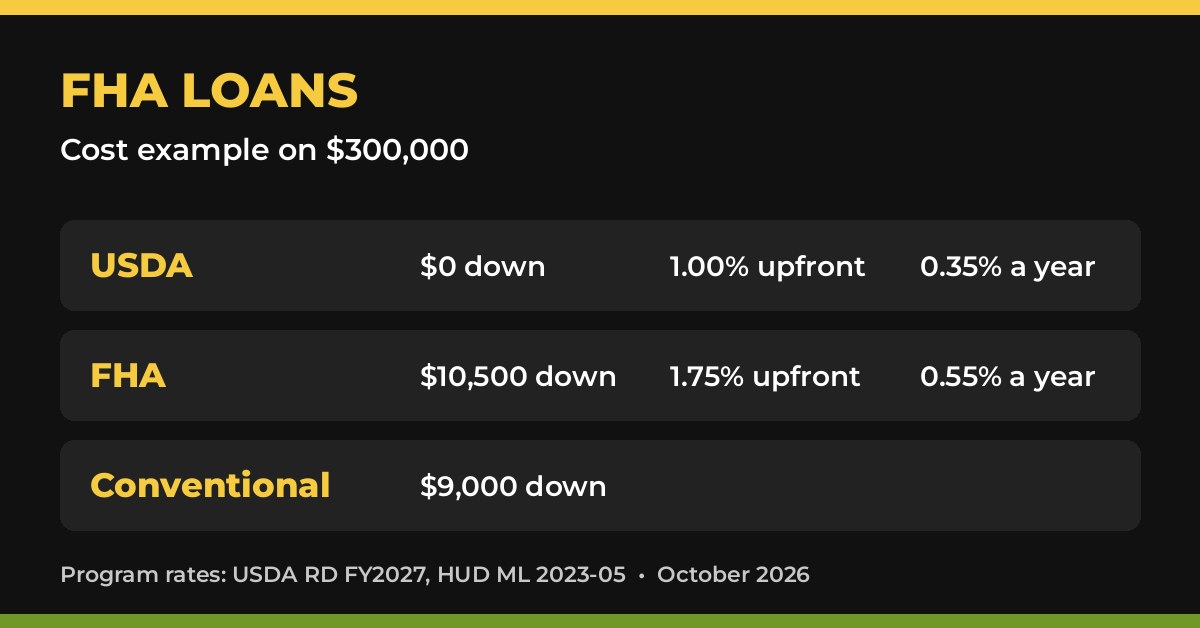
Here is simple math on a $300,000 example price, using the published program rates. It is an illustration, not a loan quote, and it leaves out interest, taxes, insurance and closing costs.
| FHA loans example on $300,000 | Down payment | Upfront fee | Annual fee, first year |
|---|---|---|---|
| USDA guaranteed | No down payment | $3,000 (1.00%)* | $1,050 (0.35%) |
| FHA | $10,500 | $5,066.25 (1.75% of $289,500) | about $1,592 (0.55%) |
| Conventional (3% down) | $9,000 | None set by the program | Varies by loan program and credit |
From our experience
*The USDA upfront guarantee fee can be paid by the seller as a seller concession, so a USDA buyer can truly put 0% down out of pocket.
Earnest money can be as little as $250 when you write an offer asking the seller to agree to your USDA 100% financing terms. The amount is negotiable and set in your purchase contract.
FHA loans by Arizona city
Buyers use FHA loans all over Arizona, from Phoenix, Mesa and Glendale to Tucson, Casa Grande and Prescott Valley. Check your county limit in the table above, then compare with our first-time home buyers guide and mortgage calculator.
Rates come from the USDA RD FY2027 fee notice and HUD Mortgagee Letter 2023-05. The FHA annual figure is an estimate on the starting balance. Ask your loan officer for a Loan Estimate, the standard three-page form the CFPB explains, to compare real offers line by line.
5 smart tips for 3.5% down FHA loans
- Get pre-approved first. A full pre-approval shows sellers your financing is ready.
- Know your county limit. Check the FHA loan limits table before you set a price range.
- Ask for seller credits. Credits can cover closing costs so your cash goes further.
- Plan for the appraisal. FHA appraisers note condition items such as peeling paint or broken railings. Your agent can spot these early.
- Layer assistance. Arizona Home Plus can provide down payment assistance with an FHA loan. See the Home Plus program page.
FHA loans and Arizona down payment assistance
The Home Plus program offers up to 4% assistance for down payments and closing costs, available statewide. Its forgivable option is a deferred second mortgage forgiven after 5 years, and at least one borrower completes a homebuyer education course. The program lists an income limit of $155,386, updated April 6, 2026, and says Home Plus is available year-round and does not deplete its funding. Ask a participating loan officer whether Home Plus can be added to your FHA loan.
First-time buyers in Maricopa and Pima counties can also ask about the Arizona Department of Housing Arizona is Home program, which serves buyers at or below 120% of area median income. Program funding can change, so confirm it is open with your loan officer.
Homes that work with FHA loans
FHA can finance single-unit homes, condos in FHA-approved projects, townhomes, 2-to-4 unit properties where you live in one unit, and manufactured homes on a permanent foundation. The home must be your primary residence. Condo buyers should ask early whether the building is on the FHA-approved list, because that can decide the loan.
If the home is a manufactured home, read our manufactured home mortgage guide for the extra FHA rules on build date, size and foundation.
FHA loans for manufactured homes
FHA can finance a manufactured home and its land together. The HUD reference guide requires at least 400 square feet, a build date after June 15, 1976, the HUD certification label, real estate classification and a permanent foundation, with a term of no more than 30 years. These homes are common in towns such as Chino Valley, Florence and Apache Junction. See our manufactured home mortgage guide for the full checklist.
FHA loans for 2- to 4-unit homes
FHA can also finance a duplex, triplex or fourplex when you live in one of the units as your primary residence. The 2026 FHA limit for a 2-unit property in Maricopa and Pinal counties is $714,000, according to the HUD FHA limit lookup. Use the same lookup for 3-unit and 4-unit limits in your county. Small multi-unit properties are scattered across older neighborhoods in Phoenix, Mesa and Tempe, and a dedicated full-time local agent can help you find them.
FHA loans compared with USDA and conventional
USDA offers 100% financing in eligible rural areas, so it beats FHA when the address and income qualify. Conventional programs such as Fannie Mae HomeReady and Freddie Mac Home Possible start at 3% down for buyers at or below 80% of area median income. FHA usually fits buyers with lower scores or higher debt ratios.
See our USDA loans guide and our first-time home buyers guide to compare all three side by side.
FHA loans FAQ
What credit score do I need for the lowest FHA down payment?
HUD allows maximum financing, or 3.5% down, with a credit score of 580 or higher. Scores from 500 to 579 are limited to 90% loan-to-value. Some loan programs set higher minimums.
What is the 2026 FHA loan limit in Maricopa County?
The 2026 FHA limit for a 1-unit home in Maricopa County is $557,750. Pinal County is the same, Coconino County is $609,500 and all other Arizona counties are $541,287.
How much is FHA mortgage insurance?
The upfront premium is 1.75% of the base loan amount. For most 30-year loans of $726,200 or less with less than 5% down, the annual premium is 0.55% for the life of the loan.
Can I use an FHA loan for a condo?
Yes, if the condo project is FHA-approved and the unit will be your primary residence.
Can I get down payment help with an FHA loan in Arizona?
Yes. Arizona Home Plus offers down payment assistance that can be paired with an FHA loan through participating loan officers.
Are FHA loans only for first-time buyers?
No. Repeat buyers can use FHA financing too, as long as the home will be their primary residence.
FHA loans official sources
Last Updated: October 2026. Every figure on this page comes from the official source linked here; we checked each one on October 16, 2026.
- HUD Mortgagee Letter 2025-23, FHA 2026 loan limits
- HUD FHA mortgage limits lookup, Arizona CY2026
- HUD Mortgagee Letter 2026-11 (Oct. 8, 2026), FHA credit score tiers
- HUD Mortgagee Letter 2023-05, FHA mortgage insurance premiums
- CFPB, FHA loans
- Home Plus program, down payment assistance and income limit (updated April 6, 2026)
- Fannie Mae, HomeReady mortgage
- Freddie Mac, Home Possible 3% down
Ready to buy with FHA loans and 3.5% down?
Tell us where you want to live. A dedicated full-time local agent will help you shop within your FHA loan limit and keep your closing on schedule.
Talk with a full-time agent about FHA financing
Tell us the city and the home type. A dedicated full-time local agent will reach out, and we can connect you with a loan officer if you want one.
Do you know anyone looking to buy or sell real estate in Arizona? Share our website with them so they are fully informed.
Call Arizona Homes and Condos Realty at (480) 490-4865 or visit ArizonaHomesandCondos.com.