Arizona loan guide • October 2026
VA Loans in Arizona: $0 Down for Eligible Veterans and Service Members
A VA home loan helps eligible Veterans, service members and surviving spouses buy a primary home or condo with little or no down payment and no monthly mortgage insurance. This VA loans guide covers Certificate of Eligibility steps, 2026 entitlement and county limits, current VA funding fee rates and how Arizona buyers compare a VA home loan with FHA and conventional options. Every figure links to an official source.
VA loans key facts
- Nearly 90% of VA-backed loans are made with no down payment (VA.gov).
- VA-backed loans do not require monthly mortgage insurance (VA.gov).
- With full entitlement, VA does not set a county loan limit; your lender still must approve the loan amount (VA.gov).
- With partial entitlement, remaining entitlement uses the 2026 FHFA one-unit conforming loan limit, which is $832,750 in most counties including Arizona (VA Circular 26-25-10; FHFA).
- Purchase funding fee, first use with less than 5% down: 2.15% of the loan amount; after first use: 3.3% (VA.gov, rates effective April 7, 2023).
- Many borrowers are exempt from the funding fee, including those receiving VA disability compensation and certain surviving spouses (VA.gov).
Talk to a dedicated full-time local agent
What a VA home loan is and how $0 down works
VA-backed Veterans home loans are made by private lenders and guaranteed by the U.S. Department of Veterans Affairs. That guaranty is why many eligible buyers can purchase with no down payment. The VA.gov home loans overview notes that nearly 90% of VA-backed loans are made with no down payment, and that you still need the credit and income your lender requires for the loan amount.
VA loans are for a primary residence. They can finance a single-family home, some condos, a townhome, or a 2-to-4 unit property when you live in one unit. There is no monthly mortgage insurance on a VA-backed loan. Instead, most borrowers pay a one-time VA funding fee unless they qualify for an exemption.
How to get a Certificate of Eligibility for VA loans
Your Certificate of Eligibility, or COE, shows a lender that you qualify for the VA home loan benefit based on your service history. Request it through the steps on VA.gov: how to request a COE. Many lenders can also pull the COE for you once you apply.
Bring your COE, recent pay statements or retirement and disability award letters, and a full picture of debts and assets when you ask for pre-approval. Pre-approval is what Arizona sellers expect before they take an offer seriously.
VA loans entitlement and 2026 loan limits in Arizona
If your COE shows full entitlement, VA does not set a county loan limit. Your lender still decides how much you can borrow based on credit, income, debts and the appraisal, as explained on the VA.gov entitlement and limits page.
If you have used entitlement that has not been restored, remaining entitlement for loans over $144,000 is based on the county’s FHFA one-unit conforming loan limit. VA Circular 26-25-10 (December 1, 2025) confirms that the 2026 FHFA limits apply to loans closed on or after January 1, 2026. FHFA set the 2026 baseline one-unit limit at $832,750 and the high-cost ceiling at $1,249,125. Arizona counties use the baseline $832,750 figure for that calculation.
Eligible buyers shop VA homes and condos across Phoenix, Mesa, Tucson, Chandler, Gilbert, Glendale, Peoria, Surprise and Sierra Vista.
Talk with a dedicated full-time local agent about pre-approval →
VA loans funding fee rates and exemptions
The VA funding fee is a one-time charge that helps keep the program available without monthly mortgage insurance. Rates on the VA.gov funding fee page (updated October 5, 2026) for purchase or construction loans are:
| Purchase or construction loan | Less than 5% down | 5% or more down | 10% or more down |
|---|---|---|---|
| First use | 2.15% | 1.5% | 1.25% |
| After first use | 3.3% | 1.5% | 1.25% |
You can finance the funding fee into the loan or pay it at closing. You do not pay the fee if you receive VA compensation for a service-connected disability, if you are eligible for that compensation but receive retirement or active-duty pay instead, if you receive Dependency and Indemnity Compensation as a surviving spouse, or if you meet the other exemption categories listed by VA, including certain Purple Heart recipients on active duty.
On a $300,000 loan with less than 5% down, a first-use funding fee of 2.15% is $6,450. After first use at 3.3%, the same loan amount would carry a $9,900 fee. That is an illustration, not a quote.
Talk with a dedicated full-time local agent about pre-approval →
VA loans cost compared with FHA and conventional
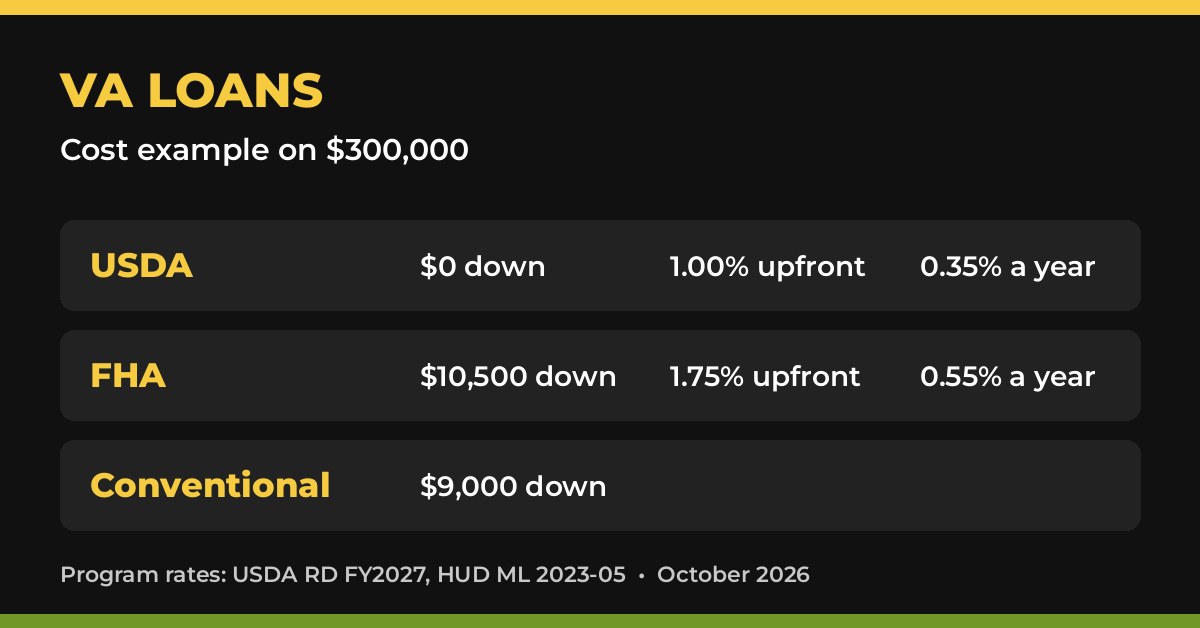
Here is simple math on a $300,000 example loan amount, using published VA funding fee rates for a purchase with less than 5% down. It is an illustration, not a loan quote, and it leaves out interest, taxes, insurance and closing costs.
| VA loans example on $300,000 | Down payment | Upfront fee | Monthly mortgage insurance |
|---|---|---|---|
| VA, first use | $0 | $6,450 (2.15%) | None |
| VA, after first use | $0 | $9,900 (3.3%) | None |
| FHA | $10,500 | $5,066.25 (1.75% of $289,500) | about $1,592 a year (0.55%) |
| Conventional (3% down) | $9,000 | None set by the program | PMI varies by lender and credit |
VA rates come from the VA.gov funding fee page. FHA figures use HUD Mortgagee Letter 2023-05. Ask your lender for a Loan Estimate, the standard form the CFPB explains, to compare real offers.
Homes and condos that work with VA loans
VA can finance a home you will occupy as your primary residence. Condo buyers should confirm early that the project meets VA lender requirements. Manufactured homes have extra rules; see our manufactured home mortgage guide if the home is factory-built.
VA allows sellers or builders to pay closing costs, and limits seller concessions to 4% of the home’s reasonable value, per VA.gov. Your agent can structure credits so more of your cash goes toward prepaid items and moving costs.
VA loans and Arizona closing-cost help
The Home Plus program offers up to 4% assistance for down payments and closing costs, available statewide. Its forgivable option is a deferred second mortgage forgiven after 5 years, and at least one borrower completes a homebuyer education course. The program lists an income limit of $155,386, updated April 6, 2026, and says Home Plus is available year-round and does not deplete its funding. Ask a participating lender whether Home Plus can be added to your VA loan.
Because many VA purchases need no down payment, assistance is most useful for closing costs and prepaid items. Seller credits are common within VA rules. For more first-time buyer options, see our first-time home buyers guide.
VA loans buyer checklist for Arizona
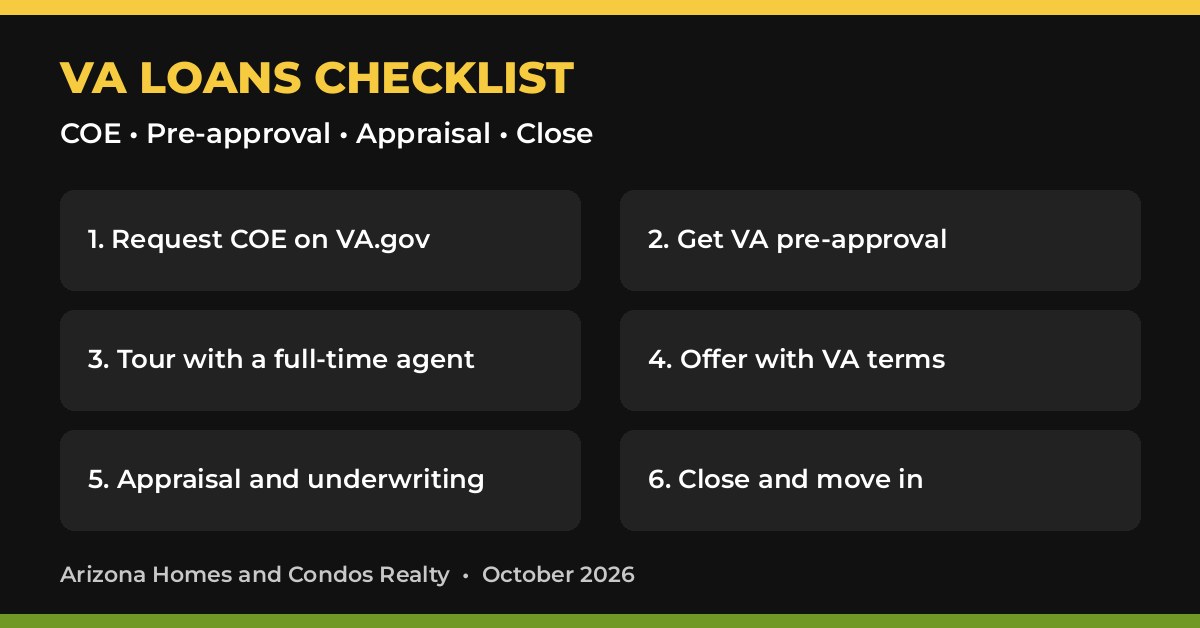
Use this checklist before you write an offer. Confirm your Certificate of Eligibility on VA.gov, complete a full VA pre-approval, and ask your agent to flag condo or appraisal issues early. Keep copies of pay statements, bank statements, divorce or support orders if they apply, and any VA disability award letter that may exempt you from the funding fee. A dedicated full-time local agent can keep the timeline tight from tour to close.
6 steps to buy with VA loans in Arizona
- Confirm eligibility. Request your COE on VA.gov or through a lender.
- Get pre-approved. Ask a VA-experienced lender to review credit, income and entitlement for your VA home loan.
- Set a price range. Full entitlement has no VA county cap; partial entitlement uses the 2026 FHFA limit math above.
- Tour with a full-time local agent. Your agent can flag appraisal and condo issues early.
- Make an offer with VA terms. Request seller credits within VA rules.
- Appraisal, underwriting and closing. Compare the Loan Estimate from your lender with any other offers you collect.
VA loans compared with FHA, USDA and conventional
VA is often the strongest fit for eligible buyers because $0 down and no monthly mortgage insurance are hard to beat. FHA needs 3.5% down with a 580 or higher score and charges mortgage insurance on every loan. USDA offers 100% financing only in eligible rural areas with an income cap. Conventional programs such as Fannie Mae HomeReady and Freddie Mac Home Possible start at 3% down and usually require private mortgage insurance under 20% down.
See our FHA loans guide, USDA loans guide, conventional loans guide and first-time home buyers guide to compare side by side. The CFPB loan options page also explains how conventional and government loans differ.
VA loans FAQ
Do VA loans really allow $0 down?
Yes. VA.gov states that nearly 90% of VA-backed loans are made with no down payment. You still need lender approval based on credit, income and the appraisal, and you may owe a VA funding fee unless you are exempt.
Is there a VA loan limit in Arizona for 2026?
With full entitlement, VA does not set a county loan limit. With partial entitlement, lenders use the 2026 FHFA one-unit conforming limit, which is $832,750 in most counties including Arizona, to calculate remaining entitlement.
How much is the VA funding fee?
For a purchase or construction loan with less than 5% down, the fee is 2.15% on first use and 3.3% after first use. Larger down payments lower the percentage. Many disability-compensation recipients and certain surviving spouses are exempt.
Do VA loans require monthly mortgage insurance?
No. VA-backed loans do not require monthly mortgage insurance. Most borrowers pay a one-time funding fee instead, unless they qualify for an exemption.
Can I use a VA loan for a condo in Arizona?
Yes, if the condo will be your primary residence and the project meets your lender’s VA requirements. Ask early before you write an offer.
How do I start VA pre-approval?
Request your Certificate of Eligibility, then complete a pre-approval with a VA-experienced lender for a VA home loan. Use the form on this page and a dedicated full-time local agent can help you connect with a lender and shop homes that fit the approval.
VA loans official sources
Last Updated: October 2026. Every figure on this page comes from the official source linked here; we checked each one on October 25, 2026.
- VA.gov, VA-backed Veterans home loans
- VA.gov, how to request a Certificate of Eligibility
- VA.gov, VA home loan entitlement and limits
- VA.gov, VA funding fee and closing costs (updated Oct. 5, 2026)
- VA Circular 26-25-10 (Dec. 1, 2025), 2026 FHFA conforming loan limits for partial entitlement
- FHFA, 2026 conforming loan limits (announced Nov. 25, 2025)
- CFPB, Understand the different kinds of loans
- Fannie Mae, HomeReady mortgage
- Freddie Mac, Home Possible 3% down
- CFPB, FHA loans
Ready to buy with VA loans and $0 down?
Tell us where you want to live. A dedicated full-time local agent will help you shop within your approval and keep your VA closing on schedule. Pre-approval starts with the form below.
Talk with a full-time agent about VA loans and pre-approval
Tell us the city and the home type. A dedicated full-time local agent will reach out, and we can connect you with a lender for VA pre-approval if you want one.
Do you know anyone looking to buy or sell real estate in Arizona? Share our website with them so they are fully informed.
Call Arizona Homes and Condos Realty at (480) 490-4865 or visit ArizonaHomesandCondos.com.