Extra Mortgage Payments: How Much Time and Interest Can You Save?
Last Updated: October 2026
Extra mortgage payments are one of the simplest ways to pay off a home loan sooner and cut the total interest you pay. The catch is that the savings are real but not linear, and the extra money only works if it goes to principal.
Below we walk through example numbers on a $400,000 loan at three illustrative rates, explain why each added payment saves less time than the one before, and show the one instruction you must give your servicer and how to check for a prepayment penalty. You can test your own numbers with our Arizona mortgage calculator.
How extra mortgage payments work
Every monthly payment on a fixed-rate loan is split between interest and principal. Early in the loan, most of the payment goes to interest because the balance is high.
When you add an extra payment and it is applied to principal, the balance drops right away. Next month’s interest is figured on that lower balance, so a little more of every later payment goes to principal. That chain reaction is the whole idea behind paying down a home loan faster.
Principal only is the instruction that matters
Extra money must be marked “apply to principal only.” If it is not, the servicer may hold it or apply it to your next scheduled payment, and you lose most of the benefit. After each extra payment, check your statement to confirm the principal balance went down.
Check for a prepayment penalty first
Some loans charge a fee for paying them off early. The Consumer Financial Protection Bureau explains what a prepayment penalty is. Check your loan documents and ask your loan officer before you start.
Extra mortgage payments: example numbers on a $400,000 loan
Example assumptions: a $400,000 loan, 30-year fixed rate, principal and interest only (no taxes, insurance or HOA dues), one extra full principal and interest payment per extra payment counted, made once a year, applied to principal only, with no prepayment penalty. Rates are illustrative examples, not quotes. Figures come from standard amortization math and are rounded.
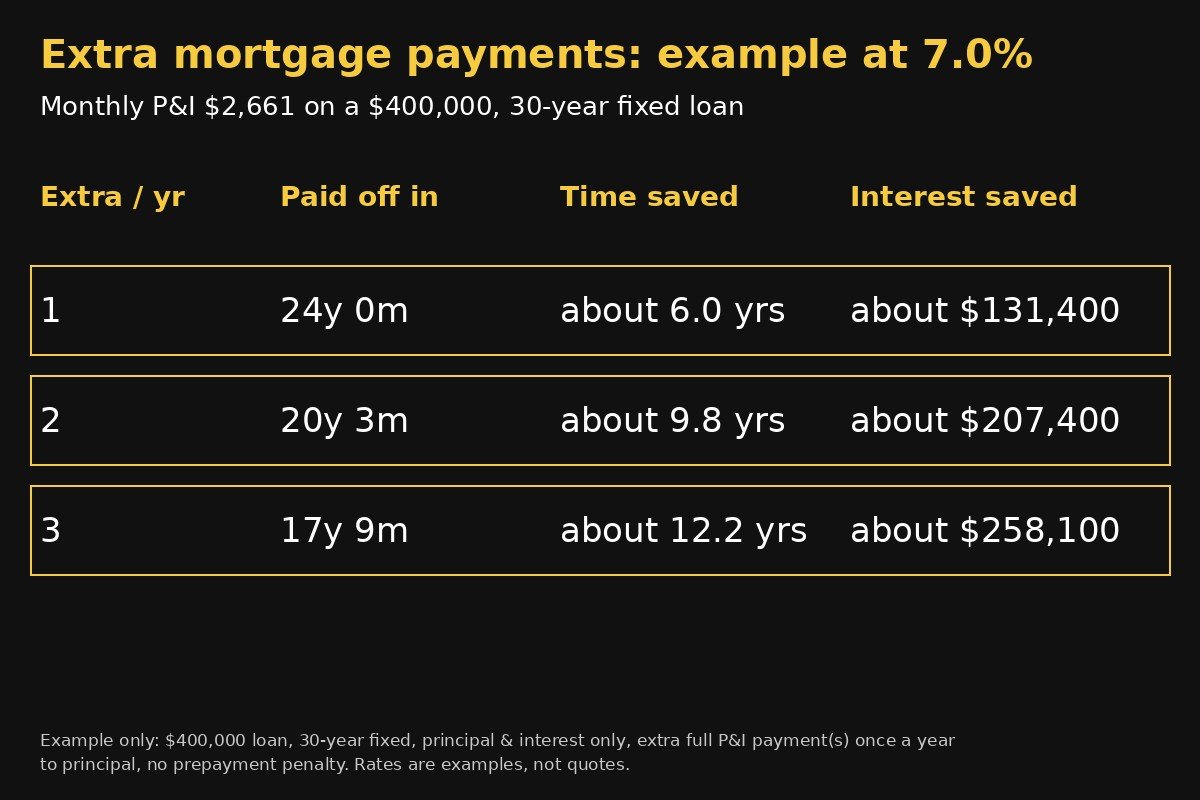
Picture this: you take out a $400,000, 30-year fixed loan at an example rate of 7.0%. Your monthly principal and interest is $2,661. Each year you send one extra full payment and mark it principal only. In this example the loan is paid off in 24 years instead of 30, saving about 6.0 years and about $131,400 in interest.
Example at 7.0%
| Extra payments per year | Paid off in | Time saved | Interest saved |
|---|---|---|---|
| 1 | 24 years, 0 months | about 6.0 years | about $131,400 |
| 2 | 20 years, 3 months | about 9.8 years | about $207,400 |
| 3 | 17 years, 9 months | about 12.2 years | about $258,100 |
Example at 6.5%
| Extra payments per year | Paid off in | Time saved | Interest saved |
|---|---|---|---|
| 1 | 24 years, 4 months | about 5.7 years | about $112,000 |
| 2 | 20 years, 9 months | about 9.2 years | about $179,600 |
| 3 | 18 years, 1 month | about 11.9 years | about $225,700 |
Example at 6.0%
| Extra payments per year | Paid off in | Time saved | Interest saved |
|---|---|---|---|
| 1 | 24 years, 9 months | about 5.2 years | about $94,600 |
| 2 | 21 years, 2 months | about 8.8 years | about $154,000 |
| 3 | 18 years, 9 months | about 11.2 years | about $195,500 |
Each row uses the same assumptions. Your own result will differ with your balance, rate, remaining term and timing of payments, so treat these as examples.
Why extra mortgage payments are not linear
You may have seen a graphic claiming that each extra payment a year cuts the same fixed number of years off a 30-year loan. The math does not work that way.
In our examples, one extra payment a year saved about 5.2 to 6.0 years. Adding a second extra payment saved about 8.8 to 9.8 years in total, and a third saved about 11.2 to 12.2 years in total. Each added payment still helps, but each one saves less time than the one before it.
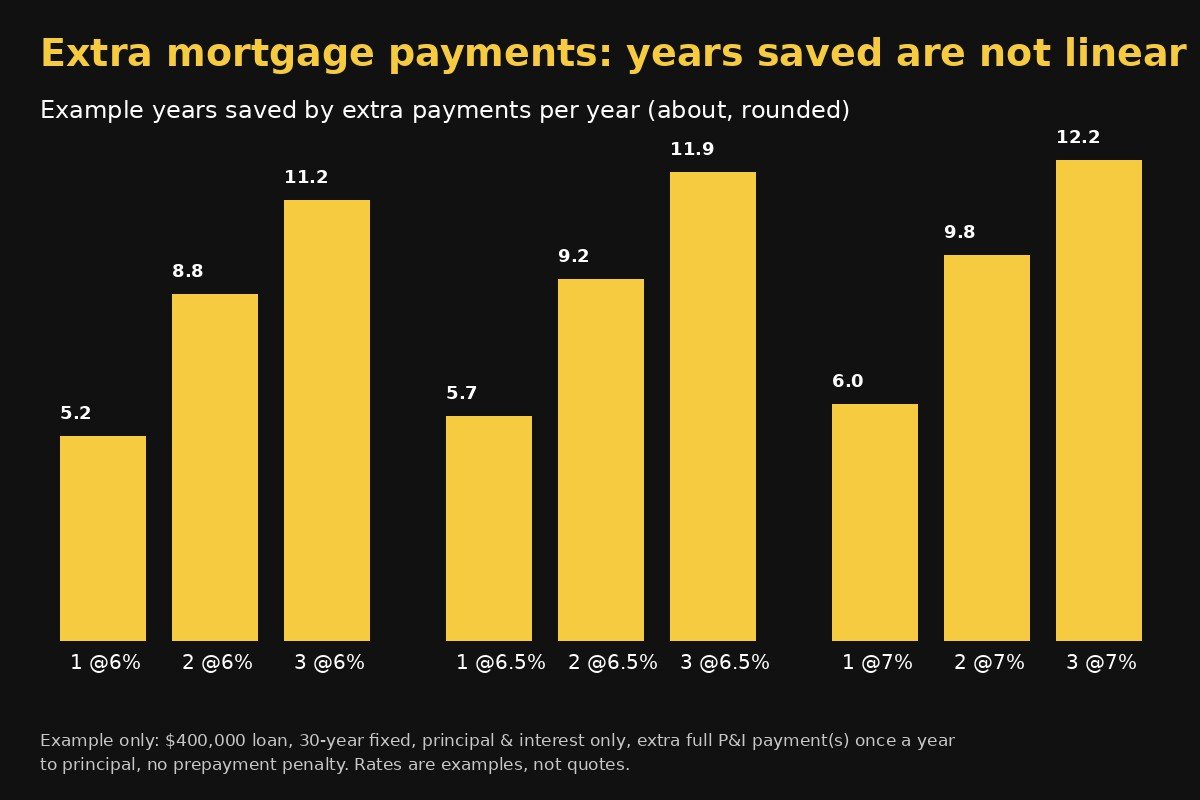
The reason is simple: the loan gets shorter as you pay it down, so there are fewer future months of interest left to cut. Savings are real, but they are not linear.
Higher rates mean bigger savings from extra mortgage payments
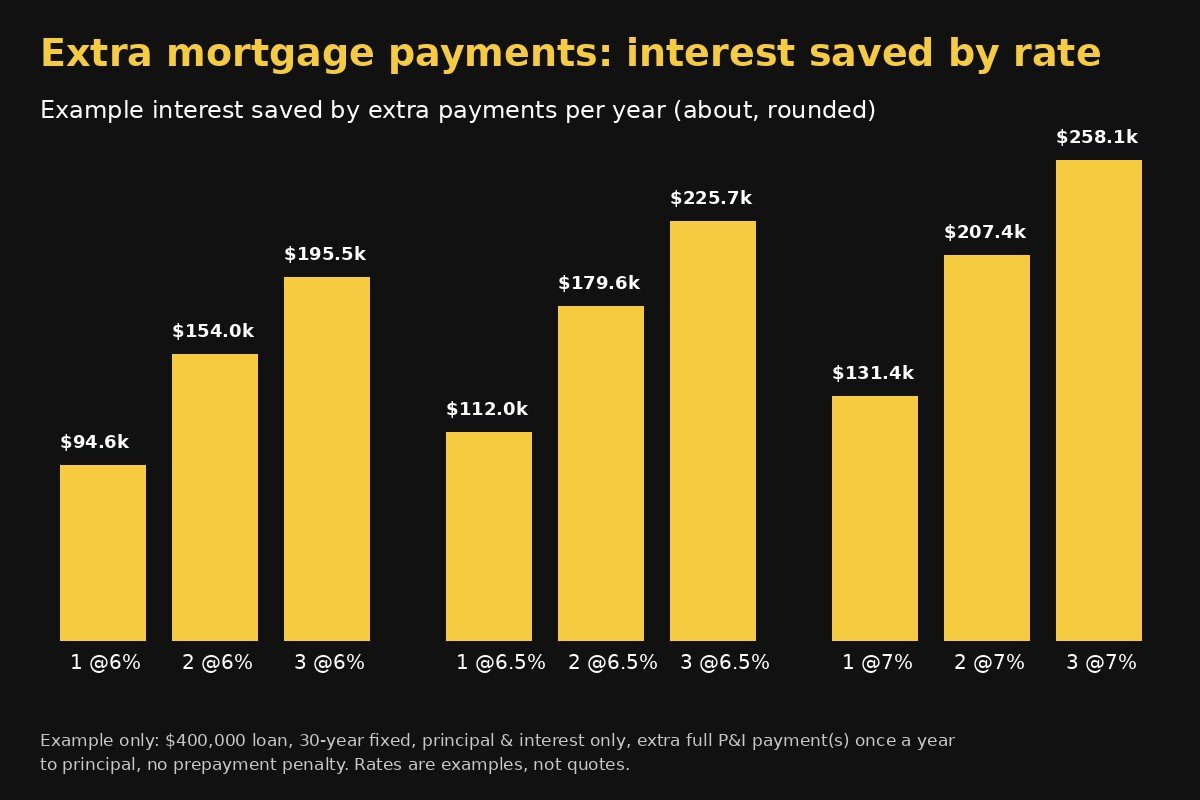
Look across the three example tables and a pattern stands out. With one extra payment a year, interest saved was about $94,600 at 6.0%, about $112,000 at 6.5% and about $131,400 at 7.0%.
With three extra payments a year, the example savings grew to about $195,500 at 6.0%, about $225,700 at 6.5% and about $258,100 at 7.0%. When more of each payment is interest, every dollar sent to principal avoids more future interest.
If you are watching rates, our post on what 7% mortgage rates mean for Arizona home prices adds market context.
Ways to make extra mortgage payments
There is more than one way to get extra money to principal. Pick the one you will actually stick with.
Pay off mortgage early without changing your loan
If you want to pay off mortgage early, you usually do not need a new loan. Each option below keeps your loan as it is and simply sends more to principal.
- Send one extra full payment once a year, such as from a bonus or tax refund, marked principal only.
- Split the extra amount across the year by adding a set amount to each monthly payment, marked principal only.
- Make a one-time principal payment when you have extra cash, then keep your regular payment the same.
- Ask your servicer how they handle extra principal and whether they offer a principal-only payment option online.
Before you set up any third-party payment program, ask what it charges and when it actually forwards money to your servicer. A fee can eat into the savings.
Before you start: questions for your loan officer
Extra mortgage payments are a personal choice. These questions help you decide whether they fit your plan:
- Does my loan have a prepayment penalty?
- How do I mark a payment as principal only, and how will it show on my statement?
- Do I have an emergency fund in place first?
- Am I carrying higher-interest debt that I should pay down before the mortgage?
- Would I rather lower my payment later by recasting the loan, if my loan allows it?
Buying your first home? Our first-time home buyers in Arizona guide covers the basics, and our FHA loans in Arizona page explains one popular option. Condo buyers can also read our Arizona condo buyer guide.
Run your own extra mortgage payments numbers
Our Arizona mortgage calculator shows a full monthly payment with taxes, insurance and HOA dues built in. Start there to see what a home really costs each month, then decide how much room you have for extra principal.
Ready to see what you qualify for? Get pre-approved with our short pre-approval form, and a loan officer can show your own payoff numbers.
Frequently asked questions
Do extra mortgage payments really save money?
Yes, when the extra money is applied to principal. In our example of a $400,000, 30-year fixed loan at 7.0%, one extra principal and interest payment a year saved about $131,400 in interest and about 6.0 years. These are examples, not quotes.
Does each extra payment a year save the same number of years?
No. In our examples, one extra payment a year saved about 5.2 to 6.0 years at the example rates of 6.0% to 7.0%, while three extra payments a year saved about 11.2 to 12.2 years in total.
How do I make sure an extra payment goes to principal?
Mark the extra money as principal only when you pay, and check your next statement. Otherwise the servicer may hold the money or apply it to your next scheduled payment.
Is there a penalty for paying off a mortgage early?
Some loans have a prepayment penalty. Check your loan documents and ask your loan officer before you start making extra payments.
Should I make extra payments or keep the cash?
It depends on your budget, savings cushion and other goals. Extra payments lower interest over time, but money sent to principal is hard to get back out of the home. Talk it through with your loan officer.
Talk to us about your next Arizona home
We help buyers across Arizona plan a home buy that fits their budget today and their goals later. A dedicated full-time local agent can walk you through homes and condos, and a loan officer can model extra payments on a real loan.
Get started with a dedicated full-time agent
Two quick steps. A full-time local agent replies personally.
Call Arizona Homes and Condos Realty at (480) 490-4865 or visit ArizonaHomesandCondos.com.